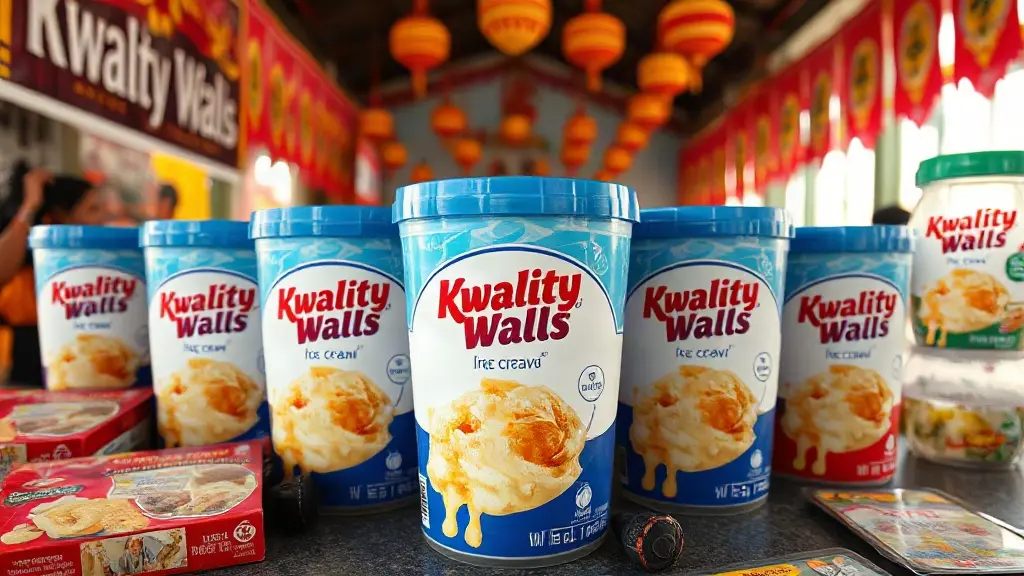
Kwality Walls shares surged 8.5% on November 13, 2026, extending a three-session winning streak and rising 94% from their March low of ₹22.25. The stock's recent performance has drawn attention as it approaches its 52-week high of ₹50.64, reached in August 2026. Despite reporting a net loss of ₹17.2 crore in Q2 FY27, the company demonstrated significant revenue growth, prompting investors to assess the stock's potential for further gains.
Recent Stock Performance and Technical Analysis
The stock opened at ₹39.65 and climbed to an intraday high of ₹43.10, reflecting renewed buying interest. Over the past month, Kwality Walls has gained 14%, with a remarkable 53% increase over the last six months. Technical analyst Jigar S. Patel from Anand Rathi Share and Stock Brokers Limited has identified key support and resistance levels: support at ₹40 and resistance at ₹43. Patel recommends a buy-on-dips strategy, advising investors to maintain a closing stop-loss at ₹40.
The stock's recent rally is attributed to a positive chart structure, as it found support near its 100-day Double Exponential Moving Average (DEMA). Patel notes that a sustained move above ₹43 could further strengthen the bullish outlook, suggesting potential for additional upside.
Q2 FY27 Financial Highlights
In Q2 FY27, Kwality Walls reported a net loss of ₹17.2 crore, a significant improvement from the ₹100.2 crore loss in the same quarter last year. Revenue from operations stood at ₹463.6 crore, with product sales amounting to ₹453 crore. The company achieved organic sales growth of 42.2%, driven by a 31.8% increase in volume and a 7.9% rise in prices. However, revenue declined 47.3% sequentially from ₹879.8 crore in Q1 FY27, when the company posted a net profit of ₹50.7 crore.
Despite the quarterly loss, the company's EBITDA before exceptional items remained positive at ₹27.2 crore, reflecting a margin of 6%. The gross margin improved by 282 basis points year-on-year to 46.4%, aided by a favorable product mix and disciplined pricing strategies, despite rising input costs associated with transitioning to dairy-based products.
Organic Sales Growth and Market Challenges
Kwality Walls achieved its highest organic sales growth in the last 16 quarters, with volumes contributing significantly to this success. The impulse portfolio recorded high double-digit volume growth, while the relaunched in-home range also saw strong performance following its transition to a richer, creamier dairy-based recipe. However, the company faces challenges from elevated milk prices and rising input costs for dairy products, driven by higher cattle feed and fodder costs and uneven rainfall affecting milk production.
The six months ending September 2026 saw revenue from operations reach ₹1,341.9 crore, with a net profit of ₹33.5 crore, compared to a loss of ₹62.6 crore in the corresponding period last year. First-half EBITDA stood at ₹132.1 crore, with a margin of 10%. These figures indicate a recovery trajectory, although the company must navigate ongoing market pressures.
Investor Sentiment and Future Outlook
Following the recent surge in share prices, investor sentiment remains cautiously optimistic. Analysts are closely monitoring whether Kwality Walls can sustain its upward momentum and surpass immediate resistance levels. The stock's ability to hold crucial support at ₹40 will be vital in determining the sustainability of the rally.
Patel's analysis suggests that the stock's positive chart structure and recent buying interest could indicate a favorable outlook. However, investors are advised to remain vigilant and consider the broader market conditions and the company's ability to manage input costs effectively.
As Kwality Walls continues to adapt to market challenges and capitalize on growth opportunities, the coming weeks will be critical in determining its trajectory. Investors should weigh the potential risks against the promising signs of recovery and growth in the company's operations.
| Forensic Metric / Statutory Dimension | Mainstream Wire Benchmark | DotMR Corroborated Record & Direct Impact |
|---|---|---|
| Q2 FY27 Net Loss | ₹100.2 crore (Q2 FY26) | ₹17.2 crore (Q2 FY27) - 83% improvement |
| Revenue from Operations (Q2 FY27) | ₹463.6 crore | ₹463.6 crore - organic growth of 42.2% |
| EBITDA Margin (Q2 FY27) | 6% | 6% - positive despite losses |
| 52-week Low | ₹22.25 | ₹22.25 - March 2026 |
| 52-week High | ₹50.64 | ₹50.64 - August 2026 |